eFX Apex
The Institutional-Grade Data Hub
- Plus: Discretionary Trades
- Edge: Sentiment Trades
- Alpha: Systematic Trades
- Apex: Full Big Data Stream


• Australian miners decline 3%, extending losses to their sixth consecutive session to hit their lowest level since early December 2025
• Copper prices sank to their weakest in seven months on Wednesday as a stronger US dollar and concerns that persistent inflation could weigh on demand triggered broad-based selling [MET/L]
• Shares of BHP and Rio Tinto fall 3.9% and 2.6%, respectively
• YTD, sub-index down 3.3%
(Reporting by Subhalakshmi Dey in Bengaluru)
Nov 19 (Reuters) - Deepening risk aversion and hawkish Federal Reserve rate expectations pummelled commodities and weighed on equity markets on Wednesday as traders braced for Anthropic's initial public offering and a series of high-level meetings between global leaders on Thursday.
Australia's October employment report leads a busy regional calendar. Markets will also monitor headlines from the APEC gathering in Shenzhen, including a trilateral summit between the US, Chinese and Russian leaders and bilateral meetings between them.
Indonesia's central bank governor and finance minister are due to speak in Jakarta after Bank Indonesia unexpectedly raised its policy rate by 25 basis points to 6.00% on Wednesday. Reserve Bank of New Zealand Assistant Governor Karen Silk is also scheduled to speak after Governor Anna Breman voiced concerns over elevated inflation.
Metals were hit hard by worries over a faster pace of Fed rate hikes after Governor Christopher Waller repeated his call for a larger half-point increase in December. The FOMC's October meeting minutesreinforced rate expectations. Copper plunged 5.3% to a seven-month low, while gold fell 3.2% to a 14-month low.
The Dow ended sharply lower and an index of global stocks fell as tech jitters spread to the broader market. Anthropic's blockbuster IPO pricing at $83 a share, above its targeted range of $70 to $78, may lift sentiment in Asia, although Moody's move to change Nvidia's outlook to stable from positive could temper any boost.
The US dollar index gained 0.2%; EUR, AUD and CAD -0.2%, JPY, CNH and NZD steady, GBP -0.45%, CHF -0.35% and bitcoin -3.3%.
Dow -1.11%, S&P 500 -0.23%, but Nasdaq +0.42% as risk aversion spread. Longer-dated Treasury yields eased; 2yr +1bp to 4.80%, 10yr -4bps to 5.066% and 30yr -5bps to 5.412%.
US crude futures closed 3.2% lower after crude and fuel inventories posted
larger-than-expected rises; they are on track for a 20% drop this month on
rising exports from the Middle East.
Asia data:
(Krisha Kumar is a Reuters market analyst. The views expressed are his own. Editing by Sonali Desai)
• NZD/USD -0.1% Thur, as ongoing hawkish Fed rhetoric lends USD support
• NZ Oct trade balance -2.77 bln (prior -1.97), exports 6.95 bln (prior 6.47)
• RBNZ Governor Breman indicates inflation still too high & recovery uneven
• Xi & Putin critical of trade protectionism ahead of meeting with Trump
• Markets focussed on Anthropic market debut, price set Wed & listing Thur
• NZD targets 0.5480-85 support, break would put 0.5469 80-month low in scope
• Range NZ 0.54875-97, support 0.5480-85 0.5469, resistance 0.5710 0.5995
NZD Daily 21/55/100-DMA
DXY Daily 55/100/200-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)
• AUD/USD -0.9% wtd as Nov downswing continues to build momentum
• AU Oct employment due 0030 GMT n, Reuters poll: +25k jobs, 4.7% unemployment
• Xi & Putin both criticise trade protectionism ahead of meeting with Trump
• Investors focussed on Anthropic market debut, price set Wed & listing Thur
• AUD targets 0.6662 ytd low, break below would accelerate downtrend
• Overnight range 0.67065-37 support 0.6662, resistance 0.7068
0.7140 0.7282
AUD Daily 21/55/100-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)
• GBP$ soft in NY afternoon trade, -0.43% at 1.3152; NorAm range 1.3173-1.3136
• Pair flirts w/Mid-October French-fiscal low at 1.3137 amid hawkish Fed shift
• Fed's Waller touts aggressive pace of hikes, perhaps +50bp to signal tougher policy
• STIR futures not pricing aggressive Fed hike in December ; +26bp indicated
• Long-end UK gilt yields moving lower, UK fiscal angst diminishing may support
• GBP$ supt 1.3136 Wednesday low/lwr 30-w Bolli, 1.3011 early Nov 2025 low
• Res 1.3209 Wed high, 1.3281 daily cloud base, 1.3319 50%
Fib of 1.3502-1.3136
GBP$ Chart:

(Paul.Spirgel is a Reuters market analyst. The views expressed are his own)
Danske Research updates its Fed rate call.
"We adjust our Fed call and expect an additional 25bp rate hike in January 2027. We still expect 25bp rate hikes in December and March, bringing the fed funds rate to 4.50-4.75% for the remainder of 2027. Growth has surprised to the upside, while the relatively tight labour market continues to expand at a solid pace. This allows Fed to focus on its inflation mandate," Danske notes.
"Inflation is broadening to non-energy components, especially services. The pickup in labour demand, will drive wage growth, and make core service inflation less like to return to target without further tightening," Danske adds.
• NY opened near 0.6725 after AUD/USD moved lower overnight, the slide extended
• Broad-based USD buying, drop sin gold, silver, copper & USD/CNH gains weighed
• The pair hit a fresh 10-month low of 0.6707 then bounced slightly
• Move down in US yields , some USD selling let AUD/USD lift
• The pair sat near 0.6720 in NY's afternoon, it traded down -0.22%
• Techs are bearish; RSIs indicate downward momentum, pair below 10- & 21-DMAs
• Australia Oct employment report is a risk during Asia
trading hours
audusd

(Christopher Romano is a Reuters market analyst. The views expressed are his own)
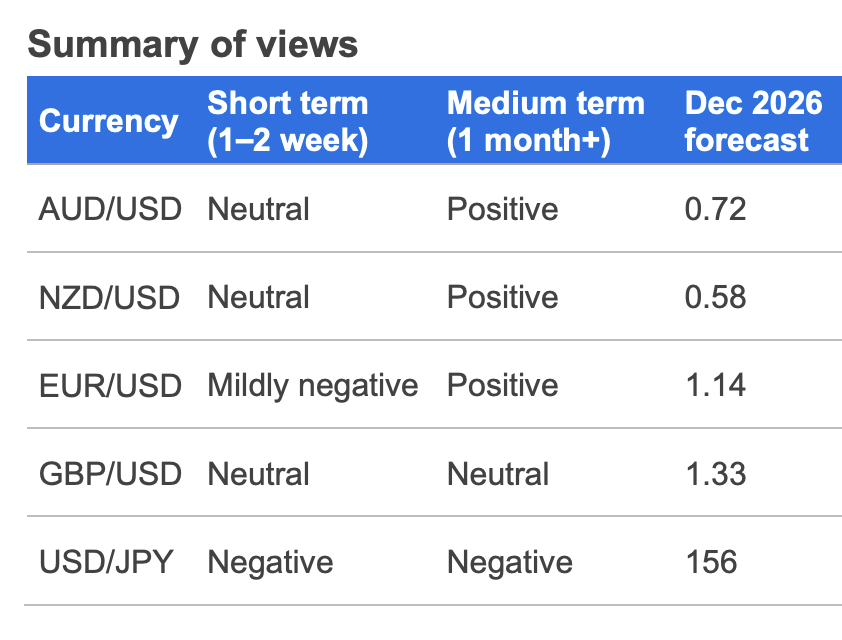
ANZ Research summarizes its views and targets for AUD/USD, NZD/USD, EUR/USD, GBP/USD, and USD/JPY.
Sterling faces continued headwinds, with today's decline to a five-week low near 1.3150 hinting at further weakness as market participants digest a flurry of economic data and shifting policy expectations, which favor more USD strength.
Today's UK data showed inflation remained elevated but ultimately did turn back the narrowing of policy divergence between the Federal Reserve and the Bank of England. This trend, coupled with robust US economic data, has broadly strengthened the dollar, pushing sterling closer to its mid-October fiscal crisis low of 1.3137. A break below this level could see bears targeting the early-November 2025 lows just above 1.30.
The dollar bid is fairly consistent across major pairs, with the tech unwind and hawkish Fed rhetoric signaling faster tightening in 2027 -- holding more sway than rate differentials alone.
There are potential silver linings for sterling. The recent drop from early November 2026 highs above 1.35 may have inflated sterling's net speculative short position, which could trigger short-covering as the year-end approaches. Additionally, LSEG's IRPR indicates that both the Fed and the BoE are likely to follow similar rate trajectories into Q4 2027, even considering the FOMC's recent hawkish lean. This could prompt recent sellers to unwind their short positions.
Still, the path of least resistance for GBP/USD appears to
be downwards. However, current futures pricing doesn't reflect
overtly hawkish Fed expectations, and despite differing guidance
from FOMC members, the central bank is unlikely to act without
clear signals from inflation data. Therefore, the established
range of 1.3137-1.35 for GBP/USD is likely to hold as markets
await December's key employment, wage, and price data.
GBP$ Chart:

(Paul Spirgel is a Reuters market analyst. The views expressed are his own)
Morgan Stanley Research discusses its USD/JPY call for 2027.
"USD/JPY sees further upside to 162. JPY is caught between the JPY-positive convergence of US and front-end rates on the one hand, and the JPY-negative impact of global risk appetite, terms of trade, and the Carry Regime on the other," MS notes.
"Ultimately we project the latter will have the larger effect, in part because we think the market will continue to see the BoJ as ‘behind the curve’, limiting the JPY-positive effect of higher local rates," MS adds.
MS targets USD/JPY at 159 in Q1, and 162 in Q4 of 2027.
(Repeat with no changes )
• FX option strikes expire at 10am New York/15:00 GMT on Wednesday November 18
• EUR/USD: 1.0960 (800M), 1.1000 (2.2BLN), 1.1010-20 (934M), 1.1025 (4.3BLN), 1.1030 (420M), 1.1050 (274M)
• USD/CHF: 0.8325 (300M). EUR/CHF: 0.9230 (390M)
• GBP/USD: 1.3125 (210M), 1.3140 (250M). EUR/GBP: 0.8350 (375M), 0.8375 (339M)
• AUD/USD: 0.6760-65 (878M). NZD/USD: 0.5480 (200M), 0.5540 (474M), 0.5575 (321M). AUD/NZD: 1.2210 (432M)
• USD/CAD: 1.4300-05 (594M), 1.4325 (212M). EUR/JPY: 176.00 (280M), AUD/JPY: 108.20 (200M)
• USD/JPY: 158.50 (724M), 159.75 (570M), 160.00 (368M), 160.50 (1BLN)
• FX options wrap - Pricing calm with a tail risk hedge (Richard Pace is a Reuters market analyst. The views expressed are his own)
• Cable eyes 1.3175 after pushing its recovery envelope from 1.3150
• 1.3175 is a former support point (Tuesday's Ldn/NY session low)
• 1.3150 was five-week low after UK Oct CPI matched 3.6% forecast
• Asian session low was 1.31885 (just before the UK inflation data)
• Democrat wins in Alaska, securing 56-44 US Senate majority
• Britain sets out scope of UK-EU summit package ahead of
Friday talks
GBPUSD

(Robert Howard is a Reuters market analyst. The views expressed are his own)
• GBP/USD option implied volatility gains have been limited by the slow pace of the USD's recent advance
• However, the benchmark 1-month expiry implied volatility at 6.0 is equal to 1-month daily realised volatility
• A repeat of the past months GBP/USD realised volatility should therefore cover current 1-month option premium
• The 1-month expiry is now Thursday December 17 and includes the Dec 16 UK CPI and Dec 17 BoE policy decision
• With 19bps priced, there's enough uncertainty to heighten
volatility risk and make 1-month options an attractive hedge
1-month expiry GBP/USD implied and realised volatility

(Richard Pace is a Reuters market analyst. The views expressed are his own)
• AUD/USD falls to 0.6712 as lower commodity prices weigh on AUD
• Gold down 2% to one-year low; copper falls to six-month low
• 0.6712 is new 10-month low (0.6720 was Tuesday low)
• Australian jobs data due at 0030 GMT; 25k f/c. Jobless rate f/c 4.7%
• RBA rate hold expected on Dec 8; Fed rate hike expected on Dec 9
• Democrat wins in Alaska, securing 56-44 US Senate majority
AUDUSD

(Robert Howard is a Reuters market analyst. The views expressed are his own)
• There appears to be growing demand to cover a EUR/USD bounce with FX options
• EUR/USD has dropped over 200 pips to lows since April 2025 in the last week and maybe running out of steam
• The market is growing more prone to a setback, and traders appear increasingly wary of that risk
• Holders of EUR call/USD put options would benefit from a snap back above 1.1000 and beyond
• Dealers say these options are being sought over the last day or two
• Related comment - Why the dollar's climb isn't moving FX
options
EUR/USD daily chart (EBS)

(Richard Pace is a Reuters market analyst. The views expressed are his own)
• Cable falls to 1.3173 as pound dips on as-expected UK Oct CPI print
• Up 3.6% year-on-year (BoE earlier this month forecast 3.7%)
• 1.3173 is four pips shy of Tuesday's five-week low
• Asian session low was 1.31885 (just before the UK inflation data)
• CPI forecast match is boost for doves opposed to BoE hike in December
• 1.3137 (11-month low on Oct 14) is a key support level
below 1.3169
GBPUSD

(Robert Howard is a Reuters market analyst. The views expressed are his own)
• FX option strikes expire at 10am New York/15:00 GMT on Wednesday November 18
• EUR/USD: 1.0960 (800M), 1.1000 (2.2BLN), 1.1010-20 (934M), 1.1025 (4.3BLN), 1.1030 (420M), 1.1050 (274M)
• USD/CHF: 0.8325 (300M). EUR/CHF: 0.9230 (390M)
• GBP/USD: 1.3125 (210M), 1.3140 (250M). EUR/GBP: 0.8350 (375M), 0.8375 (339M)
• AUD/USD: 0.6760-65 (878M). NZD/USD: 0.5480 (200M), 0.5540 (474M), 0.5575 (321M). AUD/NZD: 1.2210 (432M)
• USD/CAD: 1.4300-05 (594M), 1.4325 (212M). EUR/JPY: 176.00 (280M), AUD/JPY: 108.20 (200M)
• USD/JPY: 158.50 (724M), 159.75 (570M), 160.00 (368M), 160.50 (1BLN)
• FX options wrap - Pricing calm with a tail risk hedge (Richard Pace is a Reuters market analyst. The views expressed are his own)
• USD/CNY loses ground after a firm Wed start, last 6.6660; SSEC -0.1%
• Weighed by USD/JPY coming off on hawkish BOJ Ueda's comments
• Also pressured by UST yields subsiding further with oil prices
• USD/CNY could test 6.6614 entrance of Bollinger downtrend channel
• China's youth jobless rate drops again in Oct to 17.2%
• Was previously +18.0%, which was a reduction from prior
18.9%
CNY

(Ewen Chew is a Reuters market analyst. The views expressed are his own.)
• AUD/USD -0.1% Wed as Nvidia results induced risk sentiment relief falters
• Attention moves to Anthropic market debut, price set Wed & listing Thur
• AU Oct employment due Thur, Reuters poll: +25k jobs, 4.7% unemployment
• Trump & Xi expected to discuss trade on sidelines of APEC summit Thur
• AUD targets 0.6662 ytd low, break below will accelerate downtrend
• Range Asia 0.6722-42 support 0.6662, resistance 0.7068 0.7140 0.7282
AUD Daily 21/55/100-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)
Nov 18 (Reuters) - USD/JPY looks to be back in a range this time on the 159 handle, awaiting fresh impetus. A core range of 159.86-160.19, the EBS low Tuesday and high Friday, could contain spot action for now.
The market seems to have discounted recently more hawkish US Federal Reserve comments and at least two 25-basis-point rate hikes by the end of Q1 2027. Traders also expect potentially two 25 bp hikes from the Bank of Japan - in December and then in March 2027.
The market is also eyeing possible Japanese FX intervention on USD/JPY moves above Friday's 160.19 high and towards 161.00. The Ministry of Finance's currency czar Atsushi Mimura and Finance Minister Satsuki Katayama seem intent on stemming yen weakness towards the July 23 high of 163.99 , .
Price action in the equity markets also appears to be having an influence, with haven flows recently raising demand for the Japanese yen. The turmoil around Nvidia and concerns over other AI/hi-tech shares, data centres and hyperscaler credit have prompted many to turn to the yen as an alternative to the US dollar, for which demand had been largely boosted by interest in US shares.
Granted, the current USD/JPY stasis could quickly
disintegrate should US and global stocks take a bigger hit,
spurring fresh flows into the yen. To wit, some Tokyo pundits
fear current concerns over AI, data centres and especially
hyperscaler credit could turn into another Lehman or subprime
fiasco. Related comment .
USD/JPY:
Oil shock means ECB, Fed and BOJ are all raising rates
again:
(Haruya Ida is a Reuters market analyst. The views expressed are his own. Editing by Sonali Desai)
• AUD/USD flat Wed, unable to rally despite wage inflation acceleration
• AU Q3 wage price index +1.1% q/q (poll +0.9%), +3.5% y/y (poll +3.3%)
• AU Oct employment due Thur, Reuters poll: +25k jobs, 4.7% unemployment
• Nvidia revenue forecast above estimates, AI trade anxiety ebbs slightly
• Focus now moves to Anthropic market debut, price set Wed & listing Thur
• AUD targets 0.6662 ytd low, break below will accelerate downtrend
• Range Asia 0.67325-42 support 0.6662, resistance 0.7068 0.7140 0.7282
AUD Daily 21/55/100-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)
• After fall to 158.87 yesterday, USD/JPY bounced, Asia so far 159.39-56 EBS
• Market stuck for now between low yesterday and 160.19 last Friday?
• Bounce overnight suggests good support from area of 158.88 100-DMA
• 100-DMA descending while 200-DMA at 158.81 just below still ascending
• Resistance from now descending hourly Ichimoku cloud between 159.56-76
• Now descending 100-HMA in cloud at 159.62
• Option expiries nearby today include 158.50-92 around $1 bln below
• Above at 159.75 $571 mln, some at 160.00 and at 160.50 $946 mln
• JGB-US Treasury rate differentials tad narrower, in 2s @293, 10s @224 bps
• Fed hawkish but like the BOJ looking at leisurely, multiple 25 bp hikes
• Japanese importer bids, exporter offers, other interests to bracket spot
• Related comments , , ,
• And , also , on US data
• US markets , , ,
• On Fed-speak , , for more click on [FXBUZ]
USD/JPY:
(Haruya Ida is a Reuters market analyst. The views expressed are his own)
• NZD/USD -0.2% Wed, NZ Q3 PPI moderates in Q3 (inputs +0.7%, outputs +0.8%)
• Above estimates Nvidia revenue forecasts tempers AI trade concerns slightly
• Attention swings to Anthropic market debut, price set Wed & listing Thur
• A contingent of RBNZ officials including Governor Anna Breman speak Thur
• NZD targets 0.5480-85 support, break would put 0.5469 80-month low on notice
• Range NZ 0.5491-0.55055, support 0.5480-85 0.5469, resistance 0.5710
0.5995
NZD Weekly 52-WMA
NZD Daily 21/55/100-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)
• AUD/USD -0.3% from Tue 0.67495 high as AI trade anxiety lingers
• Nvidia results due after close Tue, Anthropic price set Wed & debut Thur
• AU Oct employment due Thur, Reuters poll: +30k jobs, 4.7% unemployment
• AUD trades 0.6720 10-month low, 0.6662 ytd low the short-term target
• Copper near 4-month lows, Gold remains close to $3,831 per ounce 1-year low
• RBA Governor Michele Bullock says inflation risks skewed to topside
• Overnight range 0.6720-48 support 0.6662, resistance 0.7068
0.7140 0.7282
AUD Daily 21/55/100-DMA
(James Connell is a Reuters market analyst. The views expressed are his own.)


